
The income required has risen by €6,000 in two years.
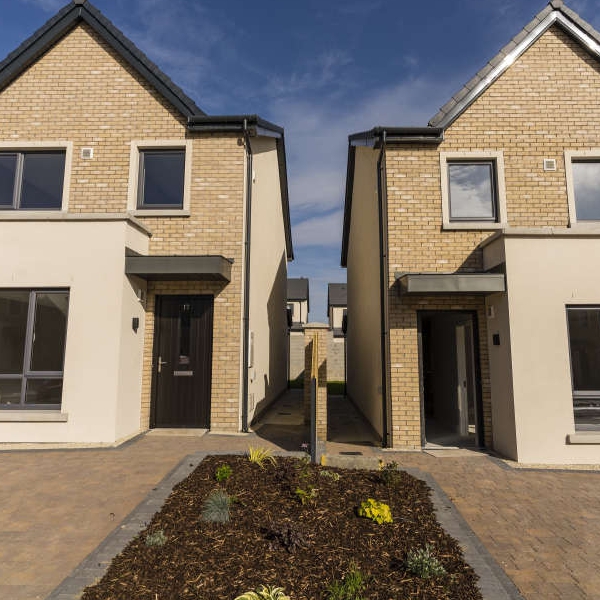
First time buyers now need a combined income of almost €80,000 to be even considered for a mortgage.
The typical household income of first-time buyers has shot up to €77,000 a year which is much higher than during the property bubble years.
In 2005, half of first-time buyers of new homes had an income of €60,000, according to the latest Mortgage Market Profile Report from the Banking and Payments Federation Ireland.
The study shows that income levels needed to secure a homeloan are the highest they have ever been, even during the Celtic tiger boom.
The income required has risen by 6,000 in the past two years alone, up from 71,000 in 2019 to 77,000 euro last year.
Brendan Burgess founder of the consumer forum Askaboutmoney.com says there are immediate ways to reduce the cost of housing:
 Orange Order Parade Delayed As Protesters Block Garvaghy Road
 Controversial Orange Order Parade For Nationalist Road Gets Go-Ahead
 Women Aged 50-65 Leaving Workplace Earlier Than Men
 Pressure On TikTok To Reveal Viewer Figures Of Harmful Content
 Taoiseach Highly Critical Of Israel In UN Address
 Gardaí To Begin Pursuit Training In December
 Tallaght Hospital's Emergency Department For Children Will Close For Four Days
 Poll Reveals Top Priorities For Voters In Upcoming Budget